Attorney or Title Company as Qualified Intermediary
Disqualified relationships can sink an exchange if the wrong intermediary is chosen.
Working out who counts as a disqualified person (such as attorneys, title companies, and other agents with a prior relationship to the investor) and why is the most important compliance question an investor must answer before choosing a Qualified Intermediary. Attorney or title company may serve as a Qualified Intermediary.
When both an attorney and a title company are disqualified, the right move is a dedicated, independent Qualified Intermediary with no prior advisory relationship to the investor. The article draws on Treasury Regulation §1.1031(k)-1(k) and the IRS disqualified person rules as its legal foundation, and it specifically benchmarks Deferred as an example of what that dedicated model looks like in practice: no exchange fee, interest shared directly with the client at published rates, every file handled by a single senior Exchange Officer with ten or more years of experience, seven-day-a-week support from 8 a.m. until midnight ET, and exchanges that can be opened in minutes. Beyond firm identity, the article ties selection to three concrete safety criteria regardless of which QI is chosen: funds held in segregated accounts under the exchanger's own taxpayer identification number, coverage from a fidelity bond plus errors and omissions insurance plus a third-party crime policy, and staff who handle exchanges as their core work rather than a sideline.
The role of a Qualified Intermediary
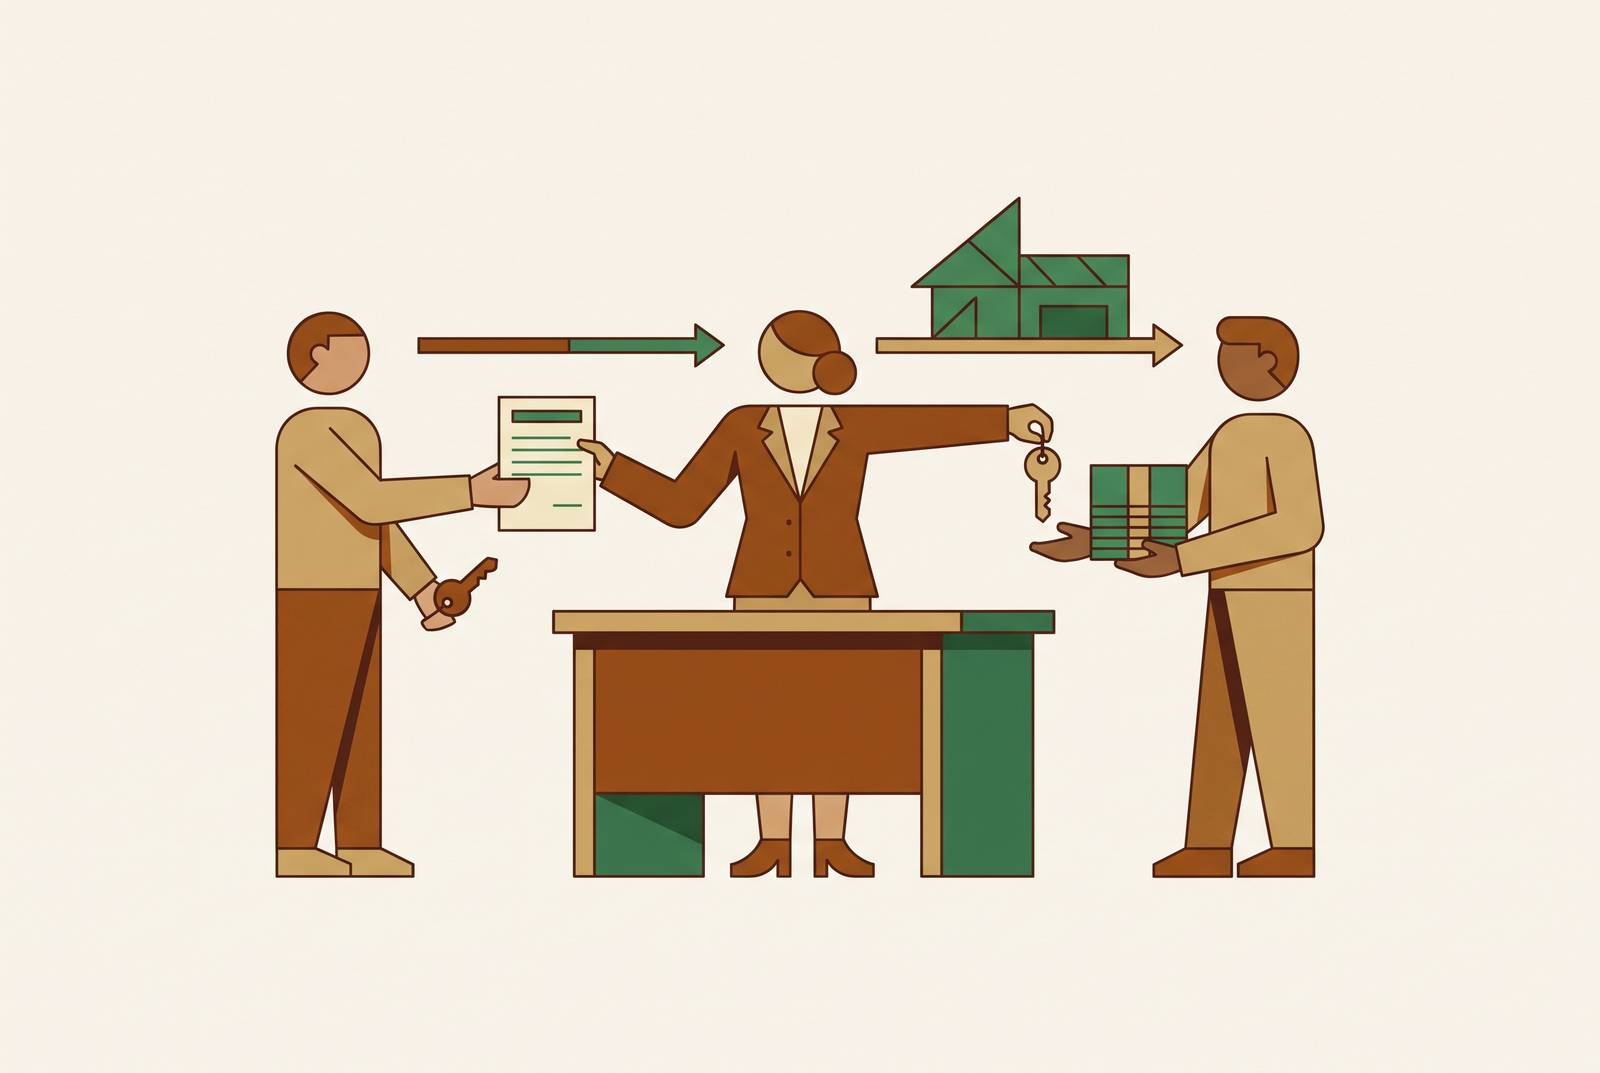
The QI is the neutral party who steps into that gap, and the IRS 'disqualified person' rule bars attorneys, title companies, and other agents with a prior relationship to the investor from serving as Qualified Intermediary. It prepares the exchange documents, takes assignment of both the sale and purchase contracts, holds the proceeds in a restricted account, and then uses those funds to acquire the replacement property on the investor's behalf. None of this is a courtesy service layered on top of the deal. It is the mechanism the Treasury Regulations built to preserve tax deferral through the use of a QI.
Timing is where the structure gets unforgiving. The QI has to be engaged and the exchange agreement signed before the relinquished property closes, because once that closing happens without an intermediary in place, there's no fixing it after the fact. A standard purchase contract might include boilerplate exchange language, but that language doesn't automatically alert the escrow or title company handling the closing. The investor has to state the exchange intent explicitly, in writing, before the deal closes.
From there, two deadlines run the clock The Ultimate 1031 Exchange Guide (2026). The investor has 45 days from the relinquished property's closing to identify replacement properties in writing, and 180 days from that same closing to complete the purchase The Ultimate 1031 Exchange Guide (2026). Neither deadline moves, regardless of holidays, financing delays, or bad luck The Ultimate 1031 Exchange Guide (2026). What's riding on hitting them is real money, including federal capital gains tax at 15 to 20 percent, depreciation recapture at 25 percent, the 3.8 percent net investment income tax, and whatever the investor's state charges on top of that The Ultimate 1031 Exchange Guide (2026). Combined, these can eat a quarter to a third of the sale proceeds if the exchange fails The Ultimate 1031 Exchange Guide (2026). So the QI isn't a formality tucked into the closing paperwork. Get the intermediary wrong, and the failure doesn't just create an administrative headache, it collapses the entire deferral and makes the full tax bill due immediately.
Why the IRS requires the QI to be independent
The regulation's whole architecture rests on one idea: the QI has to be neutral, with no loyalty running back to the taxpayer. The instant that loyalty exists, the constructive receipt risk the QI was built to solve comes right back. If the party holding the exchange funds counts, legally, as the taxpayer's agent, the IRS treats the taxpayer as having received the money directly, even if it never touched the taxpayer's own bank account. In that scenario, the intermediary offers no protection. It's simply an extension of the investor, and the exchange is a taxable sale wearing a different label.
The regulations, under §1.1031(k)-1(k), split disqualification into two categories. The first covers anyone who is an agent of the taxpayer at the time of the transaction. The second covers related parties, defined by borrowing the family and ownership tests from IRC §267(b) and §707(b), except that the ownership threshold drops from 50 percent to 10 percent. Both tests point at the same underlying concern: a QI's only role in the transaction should be facilitating the exchange itself, not managing a prior or ongoing advisory relationship with the investor. This isn't a matter of degree, and it isn't something an investor can talk their way around with good intentions or a well-drafted engagement letter. The independence requirement is structural. Either the relationship exists or it doesn't, and the regulation doesn't leave room for a version that's "close enough."
The two-year look-back rule: which prior relationships disqualify a person or firm
The Treasury Regulations name specific categories of people who count as disqualified because of a prior relationship to the taxpayer: employees of the taxpayer, attorneys who have provided services to the taxpayer, accountants who have done the same, investment bankers or brokers, and real estate agents or brokers.
The test doesn't ask how the investor felt about the relationship. It's objective and backward-looking: it doesn't matter whether the prior work felt minor, informal, or completely unrelated to real estate. What matters is whether the service happened, and when.
Related parties get swept in too, on a separate but parallel track. Family members connected by birth, marriage, or adoption are disqualified, as are entities where ownership overlaps above the 10 percent threshold set under IRC §267(b) and §707(b). Because none of this gets checked automatically by anyone else in the transaction, the burden falls on the investor.
Whether an attorney can serve as QI, the rule, the exception, and the compliance risk investors take when they ignore it
The default rule is blunt: an attorney who has provided legal services to the taxpayer at any point in the two-year look-back window is disqualified, full stop. There's a narrow carve-out, but it's narrower than most investors assume. An attorney whose services to the taxpayer have been limited solely to 1031 exchange work isn't disqualified, because that kind of limited, exchange-specific history doesn't rise to the level of general agency. In practice, that exception applies to almost nobody. Most people who've retained an attorney have gotten estate planning help, a contract review, or some other general legal service that has nothing to do with exchanges, and any of that within the look-back period trips the disqualification.
A real compliance gap becomes visible at this point. Some attorneys and CPAs have gone ahead and facilitated exchanges for clients despite having provided unrelated legal or accounting services within the two-year window, treating the arrangement as a convenience rather than a violation. It's a flagged risk in its own right. It's a flagged risk, and the exposure lands entirely on the investor's side of the table. If the IRS later determines the QI was disqualified, the exchange fails outright, and the investor owes the full deferred tax bill, plus whatever penalties and interest have accrued, regardless of how competently the attorney actually handled the exchange mechanics.
The deeper issue is structural. An attorney's fiduciary duty runs to the client, not to the integrity of the exchange process itself, and that's exactly the conflict the disqualification rule was written to prevent. Even when a trusted attorney offers to handle the role out of good faith, the investor is the one who carries the compliance risk if that attorney turns out to be disqualified. The attorney doesn't absorb the consequence. The investor does.
Whether a title company can serve as QI, the carve-out that makes routine title work different, and the caveats that remain
Title companies sit in a different position than attorneys under this rule, and the regulation says so explicitly. Routine financial, title insurance, escrow, or trust services provided by a financial institution, title insurance company, or escrow company are "not taken into account" when applying the disqualification test. A title company that closed the investor's last three property purchases isn't treated as that investor's agent on the strength of that history alone.
That carve-out narrows what counts against the title company without erasing the independence requirement. It just narrows what counts against the title company. None of its owners or its leadership can be a related party to the taxpayer under the same §267(b)/§707(b) tests that apply everywhere else in the rule. So the carve-out covers the routine closing work; it doesn't cover ownership overlap or a personal relationship between the investor and the people running the company.
Eligibility under the regulation is a different question from competence in practice, and conflating the two is where investors get into trouble The Ultimate 1031 Exchange Guide (2026). Plenty of title companies list 1031 exchange services on their website without having deep, repeated experience actually administering exchanges, which draw on specialized knowledge that routine closing work doesn't require. The sensible move is to check the title company's actual exchange track record, not just the service list, and look specifically for client feedback tied to 1031 transactions rather than general closing reviews. The regulatory carve-out was written with institutional title operations in mind. A smaller or less experienced title company handling its first exchange carries a meaningfully different risk profile than a firm that does this work as its core business.
Gaps in the disqualified person rule that leave investors exposed
The piece of the puzzle that catches investors off guard is this. The regulation defines who can't serve as QI. It says nothing about what a qualified QI has to be. There's no federal licensing requirement for the role, no mandatory bonding, no minimum capital reserve, and no experience threshold anyone has to clear. Passing the disqualified person test is a negative screen, not a credential.
The industry sits outside federal oversight, unlike banks. Exchange funds don't carry FDIC protection by default, and oversight varies widely from state to state. That gap has teeth: choosing the wrong QI can sink an exchange through a procedural misstep, or, in a worse case, lead to complete loss of the funds through fraud or mismanagement. Either outcome wipes out the tax deferral, and the investor may have no path to recover the money at all. Some states have stepped in with licensure rules, insurance mandates, or escrow account requirements. Others have none of that. So the investor's protection depends heavily on geography, and finding out the local rules before signing an agreement is worth doing.
The disqualified person rule solves a specific problem. It protects the IRS's interest in the structural integrity of the exchange, the neutrality that makes deferral legitimate in the first place. It was never designed to protect the investor's money or guarantee competent administration. Those are separate risks, and clearing the disqualification test doesn't mean either one has been addressed.
QI qualification: safety, security, and competence standards that matter in practice
Safety and competence are what separate a workable QI from a risky one, with disqualification serving only as the floor. Those are selection criteria that should carry as much weight as the disqualification checklist itself. They're the selection criteria that should carry as much weight as the disqualification checklist itself.
On the funds side, look for segregated accounts held under the exchanger's own taxpayer identification number, not commingled with the QI's operating cash. Standard FDIC deposit insurance tops out at $250,000 per depositor per institution, which is far short of what many exchanges involve. A fidelity bond protects against intentional fraud or theft, errors and omissions insurance covers procedural mistakes like a missed deadline or a misfiled document, and a third-party crime policy covers external wire fraud. A QI that can't produce all three on request is telling the investor something.
Staff competency matters just as much as the paperwork protecting the funds. Firms that specialize exclusively in 1031 work process these transactions constantly, and the sources repeatedly point to that repetition as the practical edge. Fee structure also deserves scrutiny. The traditional model has QIs retain the interest earned on held funds and charge fees of $750–$1,500 or more; Deferred instead charges no exchange fee and shares the interest earned on held funds directly with the client, publishing its rates openly in a public rate table. Deferred's model serves as a benchmark for what dedicated QI service looks like: every file is handled by a single senior Exchange Officer with ten or more years of experience from first call through closing, with no commissioned salespeople and no team handoffs, seven-day-a-week support from 8 a.m. until midnight ET, and exchanges that can be opened in just a few minutes, including at the closing table.
If My Attorney and Title Company Are Disqualified, Who Should I Use as My QI?
Start with an inventory. List every professional who has provided a service in the past two years: attorney, accountant, real estate agent or broker, investment banker, financial advisor. From there, check whether any of them have offered to take on the QI role, or whether the firm under consideration is connected to any name on that list. Run the relationship test next: is the person or entity a family member, or an entity where the investor's ownership stake exceeds 10 percent under the §267(b)/§707(b) framework?
If a title company is in the running, confirm that the prior relationship was limited to routine title, escrow, or closing work, and then, as a separate step, evaluate that company's actual track record running exchanges specifically. If an attorney is under consideration, the question is narrower and less forgiving: has every service that attorney has ever provided fallen strictly within 1031 exchange work The Ultimate 1031 Exchange Guide (2026)? Any general legal service within the past two years disqualifies them, no exceptions.
None of this works as a cleanup exercise after the fact. The QI has to be in place before the relinquished property closes, and running this test once closing has already happened is too late to undo a disqualification. The path that sidesteps both the disqualification risk and the fund-security risk at once is the same path: a dedicated, independent QI with no prior advisory relationship to the investor, funds held in segregated and fully insured accounts, transparent fees and interest practices, and staff who handle exchanges as their core work rather than a sideline. That combination is the result of checking compliance and competence separately, and refusing to let a convenient answer to one stand in for the other. It's the result of checking compliance and competence separately, and refusing to let a convenient answer to one stand in for the other.