1031 Exchange Mistakes
Primary Residence Exclusion vs. 1031 Exchange Rules
Misclassifying personal-use property can disqualify an entire 1031 exchange before it starts.
Renata Solberg
· 14 min read
Misclassifying personal-use property can disqualify an entire 1031 exchange before it starts.
DSTs let 1031 exchangers buy into institutional real estate with fixed, IRS-blessed terms.
Understanding the three types of boot and how to avoid unexpected tax bills.
The IRS lets you swap almost any U.S. real estate for almost any other.
Buying replacement property first requires parking it with a third party until the sale closes.
The clock on a 1031 improvement exchange starts before investors are actually ready to build.
Understanding boot's two forms helps investors avoid costly surprises on their tax bill.
Missing the identification rules can void your entire tax deferral.
Miss these two deadlines and your entire capital gains tax deferral vanishes instantly.
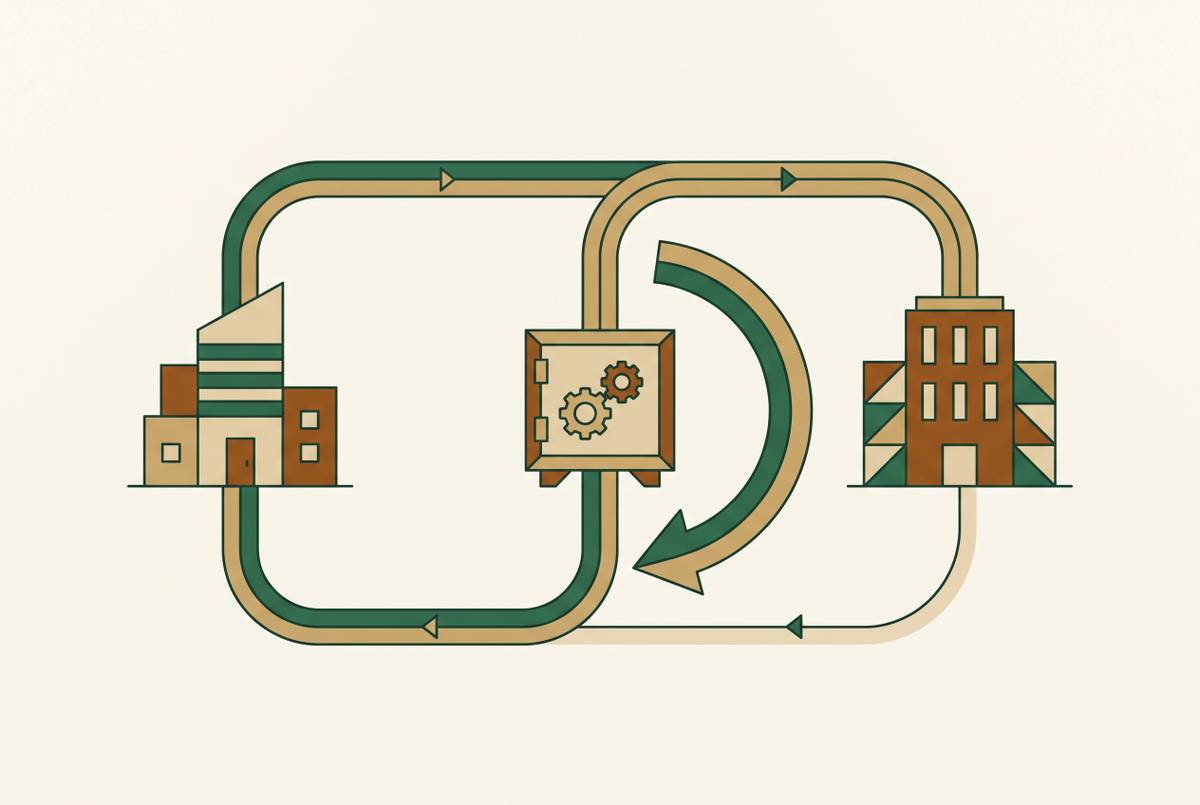
The QI prevents constructive receipt by holding proceeds until replacement property closes.
Three federal tax layers plus state levies can triple your actual bill beyond the headline rate.
Missing this deadline erases your tax deferral permanently, with no exceptions or recovery options.